
A self-custody crypto card with a strong score on cost and everyday use, and a real question mark over reliability
 Available in US
The Ethena Pay card scores 6.7 out of 10 in my assessment. On paper it is one of the more attractive crypto cards for daily spending: the virtual card is free, opening an account is free, there is no monthly maintenance fee, and spending in dollars carries no purchase fee. On the other hand, the reliability picture is the weakest of any section, because the company itself states it is not licensed or authorised by financial regulators, its official Terms do not name a card issuer, and the whole product is still a beta. So who is this card actually for? In plain terms: it suits you if you already hold USDe (or crypto you are willing to post as collateral), you live in one of the 48 countries it operates in, you are comfortable being your own bank with your own keys, and you can tolerate the rough edges of a young, invite-gated product. It does not suit you if you need a regulated, deposit-protected bank card, if you want to be able to clear your spending limit reliably regardless of market swings, or if the idea of losing a seed phrase and every dollar with it keeps you up at night.
Below I break down exactly who can get the card, what it costs in real terms, how you fund and top it up, what daily use looks like, what can go wrong, and who I would steer toward it. The conditions described here are current as of October 28, 2026.
My score for the Ethena Pay card, and who it suits
The Ethena Pay card earns 6.7 out of 10 in my review. Let me be clear about what that number means: it is an average across six things I check on every card — who can get it, what it costs, the top-up options, reliability and complaints, and everyday use. It is not a star rating from a database; it is my own read of the card as it stands today.
Here is the full scorecard, criterion by criterion, with the reason behind each mark.
| Criterion | Mark | Why |
|---|---|---|
| Who can get it | 7 / 10 | Invite-only beta in 48 countries across Latin America, the Caribbean, Asia and the Middle East, Africa and Oceania; the United States is excluded. |
| Cost | 8 / 10 | Virtual card, account opening and maintenance are free; FX on non-USD is “typically around 1.0%” at the network rate; ATM withdrawal $1.00 plus 0.65%. |
| Top-up options | 5 / 10 | You spend from a self-custody wallet holding USDe and other collateral; partners MoonPay and Iron are mentioned; specific coins and networks are not named. |
| Reliability and complaints | 5 / 10 | Ethena Pay Ltd. (Malta, C114576) states it is not licensed; no issuer is named in the Terms; unofficial reports point to Third National / Signify (Rain); a 400-user beta with few complaints found. |
| Everyday use | 8 / 10 | Virtual card in about a minute, works with Apple Pay, physical cards sit in the Standard, Pro and VIP tiers, there is an ATM; Google Pay is “available soon”; unofficial reports describe it as virtual-only. |
| Total | 6.7 / 10 | A fair card for the right person, with a young beta’s growing pains. |
Two audiences stand out. If you already hold USDe — Ethena’s dollar-pegged stablecoin — or other crypto collateral and you want to spend it in the real world across the 48 supported countries, this card was built for you. The spend debits your USDe balance directly, which is the whole point. It is less obviously aimed at someone who just wants a cheap everyday debit card with no interest in crypto at all; that reader is better served by an ordinary bank card.
Will Ethena Pay give you the card?
Yes, in 48 countries — and not in the United States. Ethena Pay runs an invite-gated beta across a wide but specific map. Let me lay it out region by region so you can check quickly:
- Latin America (17): Argentina, Belize, Bolivia, Brazil, Colombia, Costa Rica, Ecuador, El Salvador, Guatemala, Guyana, Honduras, Mexico, Panama, Paraguay, Peru, Suriname, Uruguay.
- Caribbean (12): twelve Caribbean countries and territories.
- Asia and the Middle East (8): Hong Kong, Japan, Malaysia, Pakistan, Philippines, Singapore, Thailand, UAE.
- Africa (9): Cote d’Ivoire, Egypt, Ghana, Kenya, Morocco, Senegal, South Africa, Uganda, Zambia.
- Oceania (2): Australia, New Zealand.
The United States is excluded — the card is not offered to U.S. persons. Separately, the Terms (clause 4.6) list “Restricted Jurisdictions” that include Belarus and Russia, and access is restricted for anyone “located in, ordinarily resident in, established in, or accessing the Services from” them. Note carefully what that clause keys on: it is about where you are located or resident, not your citizenship. So the restriction is a location-and-residence rule, not a nationality rule.
If your country is not on the list above, the honest answer is that Ethena Pay will not issue you this card today. The United States, the EU, the UK, Canada, Switzerland, Taiwan and South Korea are all listed as “coming soon” rather than available.
How to get the Ethena Pay card
Getting it is a three-step process: register, pass verification, and generate a virtual card, which arrives in about a minute. But the verification step is the serious one, and you should know what it involves before you start.
Ethena Pay verifies you itself or through third parties including Sumsub. Under Terms 4.8, it may ask for:
- Government-issued photo identification.
- Proof of address.
- Source-of-funds information.
- Tax data and biometric or liveness data (a selfie-style check).
You must be 18 or older, and the Terms allow one account per person. There is a single verification via Sumsub; the card’s public pages do not describe any tiers of verification beyond that. One warning worth repeating: passing the checks does not guarantee approval — verification confirms who you are, it does not promise you a card.
Once you are verified, the virtual card is generated in roughly a minute and can be added to Apple Pay. It runs on the Visa network and is denominated in dollars, and spending in USD is free. Physical cards exist in the Standard, Pro and VIP tiers, although the card’s public pages do not state which countries they ship to, how long delivery takes, or what delivery costs — that detail is not stated.
One important caveat here, and I will flag it because it comes up in the questions people ask me: an unofficial source (CryptoCardHub, September 2026) describes the card as virtual-only with no physical option, which disagrees with the official page listing physical cards in the three tiers. I have gone with the official page, but if having a plastic card in the post matters to you, confirm it directly with support rather than trusting either version.
What the Ethena Pay card really costs: Fees
Short version: the everyday costs are genuinely low, and the two fees you are most likely to meet are a roughly 1% foreign-exchange cost when you spend outside dollars and a $1.00 plus 0.65% charge when you take cash out at an ATM. Account opening, monthly maintenance, and the virtual card itself are all free.
Here is the full cost picture, drawn only from what the card publishes:
| Fee or limit | Amount |
|---|---|
| Virtual card issuance | Free |
| Card replacement | Free |
| Card activation | Free |
| Account opening | Free |
| Monthly maintenance | Free |
| Minimum balance | None |
| Inactivity fee | None |
| Spending in USD | No purchase fee |
| Foreign-exchange (non-USD) | “Typically around 1.0%”, passed through from the card network at cost (not a cap or guarantee) |
| Cross-border fee | None |
| Interest on purchases | 0.00% |
| Late payment fee | Up to $40 |
| Returned payment fee | Up to $29 |
| Cash withdrawal (ATM) | $1.00 plus 0.65% of the amount (ATM operator may add its own surcharge) |
| Third-party costs | Gas and funding-partner fees are separate |
| Crypto conversion fee | Not stated |
Let me walk through three everyday payments to make these numbers real, because percentages only mean something once you attach them to a purchase.
Buying lunch for $20 while in the United States. You spend in dollars, so there is no purchase fee and no FX conversion — the $20 comes straight off your balance. The only cost is whatever the network fee was to move your USDe to the spendable balance, and that is on the crypto side rather than the card fee schedule. This is the cleanest case: dollar spending inside the dollar network is free on the card side.
Buying a €30 book while travelling in Europe — except you cannot. The card is not offered in the EU, so this exact trip is out of scope for the card itself. Take the same purchase in a supported non-dollar country instead, say a ¥5,000 meal in Japan. Because the card is a dollar card, the yen amount is converted at the network rate and the card network’s cost is passed through at “typically around 1.0%.” That 1% is not a guaranteed cap — it is what the network typically charges at that moment — and there is no separate cross-border fee on top. So the ~1% is essentially your one-time cost on a foreign purchase, which is competitive with, or better than, many mainstream cards.
Taking $100 out of a cash machine in Mexico. Here the fees stack in a way that matters if you use ATMs often: you pay $1.00 plus 0.65% of the amount, so a $100 withdrawal costs $1.00 plus $0.65, i.e. $1.65, before the ATM operator adds its own surcharge on top. That surcharge is set by the ATM owner, not by Ethena Pay, and it varies. Availability of the ATM feature also depends on your eligibility. The general lesson: card purchases are cheap, but repeated ATM withdrawals are where the cost concentrates.
I will flag the cost outliers honestly too. An unofficial user report (CryptoCardHub, September 2026) from a Philippines user says the app quoted a $10 charge for a first card. The official schedule says the virtual card is free, so this reads as an isolated report, possibly a physical card or a partner fee, but it is a reminder that a partner-app quote can differ from the published schedule.
How to top up the Ethena Pay card
Topping up is where this card is genuinely different, and it is worth understanding before you apply. Ethena Pay is self-custodial. Your USDe and supported digital assets sit in a wallet you control, they are posted as collateral, and when you spend, the card debits your USDe balance. There is no bank account behind the card in the traditional sense — the card draws down crypto you already hold.
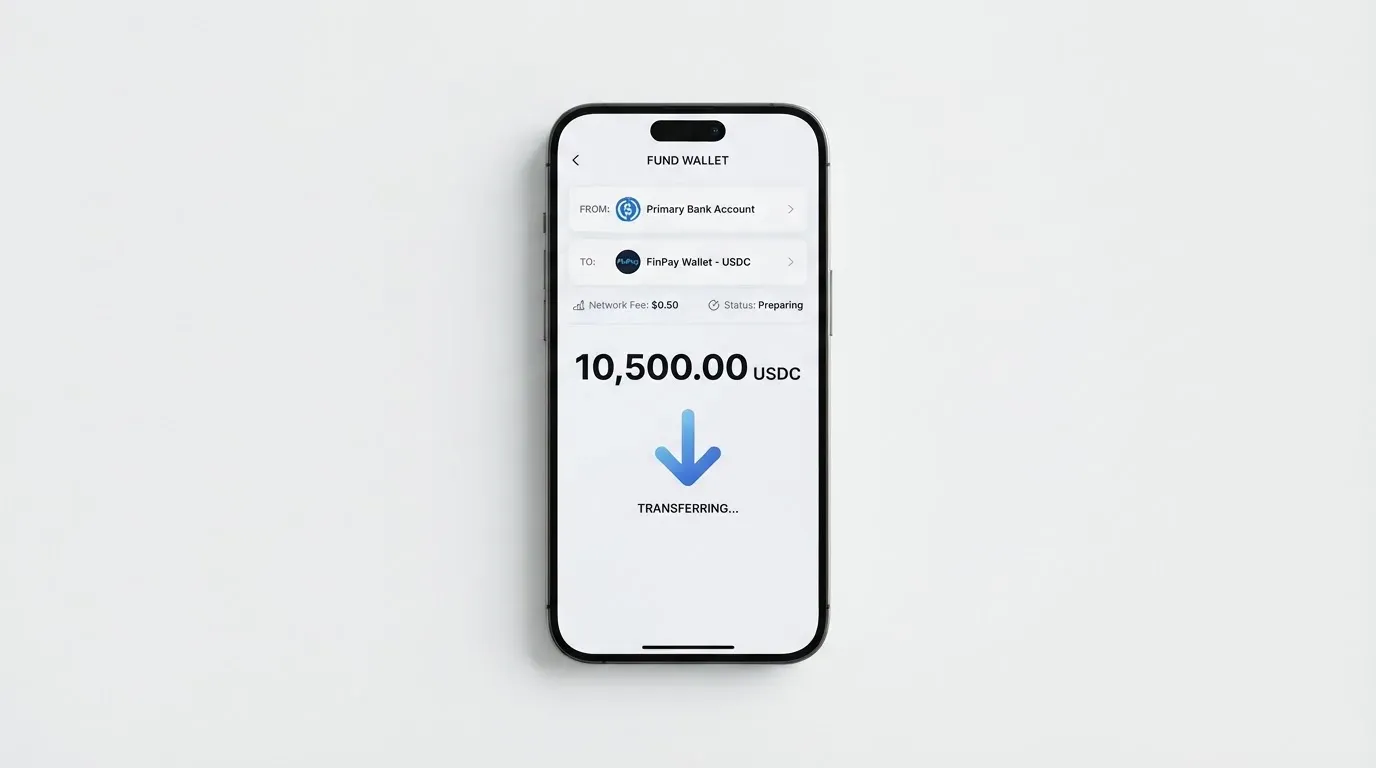
In practice that means:
- Your wallet is the balance. You hold USDe and other supported digital assets as collateral, and spending takes USDe off that balance.
- Sending to other Ethena Pay users is free. A transfer to another Ethena Pay user costs nothing on the card’s side.
- Funding partners exist. MoonPay and Iron are named as funding partners you can go through.
- No deposit fee is published, and the minimum top-up is not stated. The card’s public pages simply do not give you a number here.
- Third-party funding fees are separate. Whatever MoonPay, Iron or the network charges for getting funds in is on top, not included.
Two details to keep in mind. First, the specific coins and networks supported for funding are not named on the card pages — the app launched on Avalanche per The Defiant’s headline, but that is not a promise of your funding options. Second, and this is the self-custody catch: because the funds are yours, there is no custodial safety net. If you lose your keys, the money is gone — the Terms are explicit that Ethena Pay “doesn’t hold your funds, keys, or seed phrases,” offers no custodial or safeguarding service, and cannot recover lost keys. And because blockchain transfers are irreversible, sending on the wrong network or to a wrong address can mean the deposit is simply lost or needs manual recovery with no guarantee. On withdrawal specifically, the card’s public pages do not state a policy — what is stated is that keys and funds stay with you and that sending to another Ethena Pay user is free.
Paying with the Ethena Pay card every day
Day-to-day use is the card’s strongest suit, and this is where it scores an 8. The virtual card generates in about a minute and drops straight into Apple Pay, which is the wallet most iPhone users want. Google Pay is described as “available soon,” so if you are on Android, your experience today is more limited. There is an iPhone app, currently in beta.
The reward is cashback paid in AVAX, credited daily after settlement, structured in monthly spend bands per tier:
| Tier | Top band | Next bands |
|---|---|---|
| Standard | 4% on the first $2,500 monthly | 1% on $2,500–$4,000; 0% above that |
| Pro | 4.5% up to $8,000 | then 2%, 1%, 0.5% |
| VIP | 5% up to $20,000 | then 2%, 1%, 0.5% |
A few rules on the cashback so you know what does not count:
- Transactions under $1.00 earn nothing.
- Refunded purchases reverse the cashback you earned on them.
- Cashback is excluded from: cash advances, ATM withdrawals, crypto/stablecoin/NFT/securities purchases, gambling, gift cards, peer-to-peer payments, and account funding.
- The Daily Boost pays interest on your balance (Standard 5% per annum up to $5,000; Pro and VIP 6% per annum up to $100,000 and $1,000,000) but requires one card transaction per month. Pro is reached via a subscription or referrals.
On refunds and disputes: refunded, charged-back or ineligible purchases reverse their cashback and drop out of your monthly spend. A chargeback can be deducted from your balance, and if that drives the balance negative, the negative amount remains your liability. Complaints are acknowledged within five business days, with a final response targeted within fifteen; the card’s public pages do not state chargeback time frames.
What can go wrong with the Ethena Pay card
The reliability score of 5 is the part I would want you to read twice. There are four separate things bundled into that mark, and none of them is a scandal — but together they add up to “young beta, not a finished bank.”
1. The company states it is not licensed. Ethena Pay Ltd. is a Maltese limited company, number C114576, registered in Ta’ Xbiex, Malta. It says plainly that it is “not licensed, registered, authorized, or otherwise approved” by financial regulators, and that it works through Third-Party Providers. So you are not dealing with a licensed bank or e-money institution in the regulatory sense, and the card’s public pages do not name a card issuer in the official Terms.
2. The issuer is unclear. Unofficial reporting (CryptoCardHub, September 2026, and The Defiant) identifies the Visa card as issued by Puerto Rico-chartered Third National and managed by Signify Holdings (Rain). This is not confirmed by the card’s official pages, so treat it as unofficial — but it is at least a plausible answer to “who issues the card.”
3. Self-custody means self-risk. You hold the keys. Nobody can reverse a mistaken transfer or recover lost keys. That is the trade you make for the card not holding your funds.
4. The beta is very young. Ethena Pay launched on Avalanche as an iOS beta with 400 early users (The Defiant). An invite-gated beta began 1 September 2026 across 49 countries (CryptoCardHub, page updated 24 September 2026). Version 1.3.0 improved notifications, limits, cashback and verification — which tells you the product is still being tuned.
On complaints: officially, no incidents were found, and no Trustpilot or Reddit pages surfaced in a single search. The only user-facing reports I could find are editorial ratings (SpendNode 3.9/5, September 2026) and that one isolated $10 first-card charge from a Philippines user. So there is no complaint backlog, but there is also barely any track record — a beta this young has not been stress-tested by time. Treat the absence of complaints as “not enough data,” not as “proven reliable.”
One more limit to understand before you rely on the card day to day: spending limits are dynamic. The official pages list no fixed spending cap, only the Daily Boost balance caps per tier, and note that transaction limits may be imposed and changed without notice (Terms). Unofficial reporting (CryptoCardHub, September 2026) goes further and says the spending limit is tied to collateral value and can be reduced even to zero. That matters: if your collateral is volatile or drops, your ability to spend can drop with it.
What to take instead
If Ethena Pay’s model does not fit you — unlicensed provider, self-custody risk, or a limit that moves with your collateral — there are two other crypto cards I looked at, plus the honest option of an ordinary bank card.
Sponge scores 4.9 out of 10 in my assessment, and it is the weakest of the three. You spend USDC collateral moved from the Sponge wallet (for example on base, with the SDK mentioning base or solana). It is described on the homepage as a credit card issued by Rain, a Visa Principal Member, accepted wherever Visa is accepted, created via a createSpongeCard function. But much of what I check is simply not stated: no country list on the card pages, no costs, no fees, no rewards. Its platform terms set a minimum age of 13 for the service. The low score reflects thin disclosure, not a discovered flaw.
Nexo scores 6.3 out of 10 and is the most conventional of the three. It serves residents and citizens of “selected European countries, including the EEA and the United Kingdom” — note the wording covers both citizens and residents, and no specific country list appears on the page, with certain unnamed jurisdictions excluded. You get a virtual card (activates in the app) and a physical one, issued by DiPocket UAB, with a Mastercard trademark notice on the page though the network is not stated explicitly. Its costs are clearly laid out: no monthly, annual or inactivity fee; the virtual card needs at least $50 in the account to activate; the physical card has free shipping but requires a balance above $5,000 in digital assets and at least Gold tier. FX is 0.2% on weekdays (EEA/UK/CH) and 2% rest of world, rising to 0.7% and 2.5% on weekends. Cashback is only on purchases in Credit Mode with more than $5,000 in digital assets, paid in NEXO tokens or Bitcoin by tier. One piece of news to weigh, not official: Cointelegraph reported a 2025-era Bulgarian police raid on Nexo’s Sofia office over alleged sanctions/AML violations, with no official Nexo statement on Russians found.
Xplace scores 7.7 out of 10 and is the strongest of the alternatives on the numbers. It is a Visa card, virtual (instant) and physical (Silver is live; Gold/Platinum coming soon, delivery 7–14 business days), with a Cash mode that spends a stablecoin balance and a Credit mode that borrows against your holdings. You can deposit BTC (cbBTC), ETH (wETH), SOL, JitoSOL, USDC, USDT and xStocks on the Solana network. Credit-mode cashback runs by tier: Basic 0.5%, Silver 1%, Gold 1.5%, Platinum 2%, paid in USDC to the wallet at settlement; Cash-mode cashback is not stated. Annual fees: Basic free, Silver $99, Gold $249, Platinum $999, with no borrowing origination fee. It advertises “0% FX on Platinum” and “no hidden spread” on stablecoin spending, though FX for other tiers and the conversion fee are not stated. Its country list is also not stated, with a general note that services are not available in all jurisdictions, and Visa acceptance in 160+ countries.
The comparison, briefly:
| Card | Score | Cost shape | Best for |
|---|---|---|---|
| Ethena Pay | 6.7 / 10 | Free virtual card; ~1% FX; ATM $1.00 + 0.65% | USDe holders spending across 48 countries |
| Sponge | 4.9 / 10 | Not stated | Users of USDC on base who accept thin disclosure |
| Nexo | 6.3 / 10 | No monthly fee; FX 0.2%–2.5%; $5,000+ for physical | European residents wanting a conventional regulated feel |
| Xplace | 7.7 / 10 | Free Basic; tier fees to $999; 0% FX on Platinum | Solana users; credit-mode cashback seekers |
If you want a no-nonsense summary: Xplace currently scores highest, but its credit model and Solana focus are different from Ethena’s spend-stablecoin model. Nexo suits European residents who prioritise clarity and a regulated-issuer feel. Sponge is hard to recommend on disclosure alone. And if you do not need crypto spending at all, an ordinary bank card remains the most regulated and often the cheapest option.
Who I would recommend Ethena Pay to
I would recommend this card, with eyes open, to three kinds of people. First, if you already sit on USDe or crypto collateral and want to convert that into everyday spending without selling to a bank first, the self-custody model is a genuine fit and the free dollar spending is hard to argue with. Second, if you live in one of the 48 supported countries, are comfortable with on-chain self-custody, and understand that a beta product’s limits and features can shift — you can be an early, informed user rather than a guinea pig. Third, if you value the no-monthly-fee, no-purchase-fee structure and rarely use ATMs; in that profile the effective cost is near zero for dollar spending and about 1% abroad.
I would not recommend it if you need any of the following: a deposit-protected bank account; confidence that a named, regulated issuer stands behind the card; a stable, predictable spending limit that does not move with your collateral; Google Pay today; a physical card in a supported country with clear delivery terms; or a service with a long public track record. Nor would I recommend it to anyone uneasy about self-custody — if losing a seed phrase losing all your money is a dealbreaker, this is the wrong architecture, whatever the card’s fees look like.
The bottom line: Ethena Pay is a credible, cost-effective spend card for the right person, built on a young and explicitly unlicensed foundation. That combination is fine for an early adopter who understands the trade, and wrong for anyone who needs the full weight of a regulated bank behind their money.
Frequently asked questions
What is Ethena Pay card?
The Ethena Pay card is a Visa payment card that spends from a self-custodial crypto wallet rather than a bank account. You hold USDe and other supported digital assets as collateral in a wallet you control, and when you make a purchase the card debits your USDe balance directly. A virtual card is generated in about a minute and can be added to Apple Pay, and physical cards sit in the Standard, Pro and VIP tiers. It is currently an invite-gated beta across 48 countries, excluding the United States.
How does the Ethena Pay card work?
It works as a prepaid-style card on top of your own wallet. Your crypto stays in a self-custodial wallet, the balance is posted as collateral, and each tap debits the USDe portion. Spending in USD is free, while non-USD spending is converted at the network rate with the network’s cost — typically around 1% — passed through. You can fund through partners like MoonPay and Iron, and sending to other Ethena Pay users is free.
Is Ethena Pay a bank?
No, it does not present itself as a bank. Ethena Pay Ltd. is a Maltese company that states it is “not licensed, registered, authorized, or otherwise approved” by financial regulators, working through Third-Party Providers. So it is not the same as holding money at a deposit-protected bank, and the card’s official Terms do not name a card issuer. Treat it as a crypto spending tool, not a bank account.
Who owns Ethena Pay?
Ethena Pay is operated by Ethena Pay Ltd., a Maltese limited company registered under number C114576 in Ta’ Xbiex, Malta. Unofficial reporting (CryptoCardHub, September 2026, and The Defiant) identifies the Visa card as issued by Third National, a Puerto Rico-chartered institution, and managed by Signify Holdings (Rain), but this issuer detail is not confirmed on the card’s official pages. The operating company itself is the Maltese entity above.
Does the Ethena Pay card require KYC?
Yes. Under Terms 4.8, Ethena Pay verifies customers itself or via third parties including Sumsub, and may request government-issued photo identification, proof of address, source-of-funds information, and tax and biometric/liveness data. You must be 18 or older, and one account is allowed per person. Note that passing the verification checks does not by itself guarantee that your application will be approved.
How much does the Ethena Pay card cost?
The core costs are low: the virtual card, its replacement and activation are free, as are account opening and monthly maintenance, with no minimum balance or inactivity fee and no fee on dollar purchases. The fees you are most likely to meet are roughly 1% on non-USD spending (passed through at the network’s cost, typically) and $1.00 plus 0.65% for an ATM withdrawal, plus any ATM operator surcharge. Late payments can cost up to $40 and returned payments up to $29.
Can I use the Ethena Pay card in my country?
That depends where you are. The card covers 48 countries across Latin America (17, including Brazil, Mexico and Argentina), the Caribbean (12), Asia and the Middle East (8, including Japan, Singapore, UAE and Hong Kong), Africa (9) and Oceania (2). It is not offered to U.S. persons. The United States, EU, UK, Canada, Switzerland, Taiwan and South Korea are listed as coming soon, so if you are in one of those, you cannot use it today.
How do I top up the Ethena Pay card?
Topping up means getting crypto into your self-custodial wallet, because that wallet is the balance the card spends from. You can fund through partners such as MoonPay and Iron, or send to other Ethena Pay users for free. No deposit fee is published and the minimum top-up is not stated. Be aware that third-party funding fees and network gas are charged separately, and that sending on an unsupported network or to a wrong address can be irreversible.
Is the Ethena Pay card safe and worth it?
It is worth it for the right person and neither safe nor complete for everyone. On the safe side, your funds and keys stay with you — Ethena Pay says it does not hold them — and there is no custodial counterparty to hack. On the caution side, the provider is explicitly unlicensed, the issuer is not named officially, self-custody makes key loss unrecoverable, and spending limits can move with your collateral. Treat it as a young beta, not a bank.
How do I add the Ethena Pay card to Apple Wallet, and is Google Pay supported?
Adding it to Apple Pay is part of the normal setup: once your virtual card is generated — it takes about a minute — you add it to Apple Pay and start tapping. Apple Pay is fully supported today. Google Pay, however, is only described as “available soon,” so if you are on an Android phone, mobile wallet support is not there yet. That, plus the virtual-first design, is worth knowing before you sign up for a card you hoped to use on your phone.
Credit and cashback cards in the catalogue – cryptocardcatalog
Content created by the «cryptocardcatalog» team